


Schaumburg Marketplace
Connecting Local Business
And Empowering Community
951 N Plum Grove Rd, Suite C
Schaumburg, IL 60173
◆ CONNECTING LOCAL BUSINESS · EMPOWERING COMMUNITY


Economy
Fed survey shows higher median income, modest wealth gains and more strained borrowers
The Federal Reserve’s 2025 Survey of Consumer Finances shows median family income rose after inflation, but debt stress increased for some households.
October 16, 2026 · 5 min read
I'm a paragraph. I'm connected to your collection through a dataset. Click Preview to see my content. To update me, go to the Data Manager.
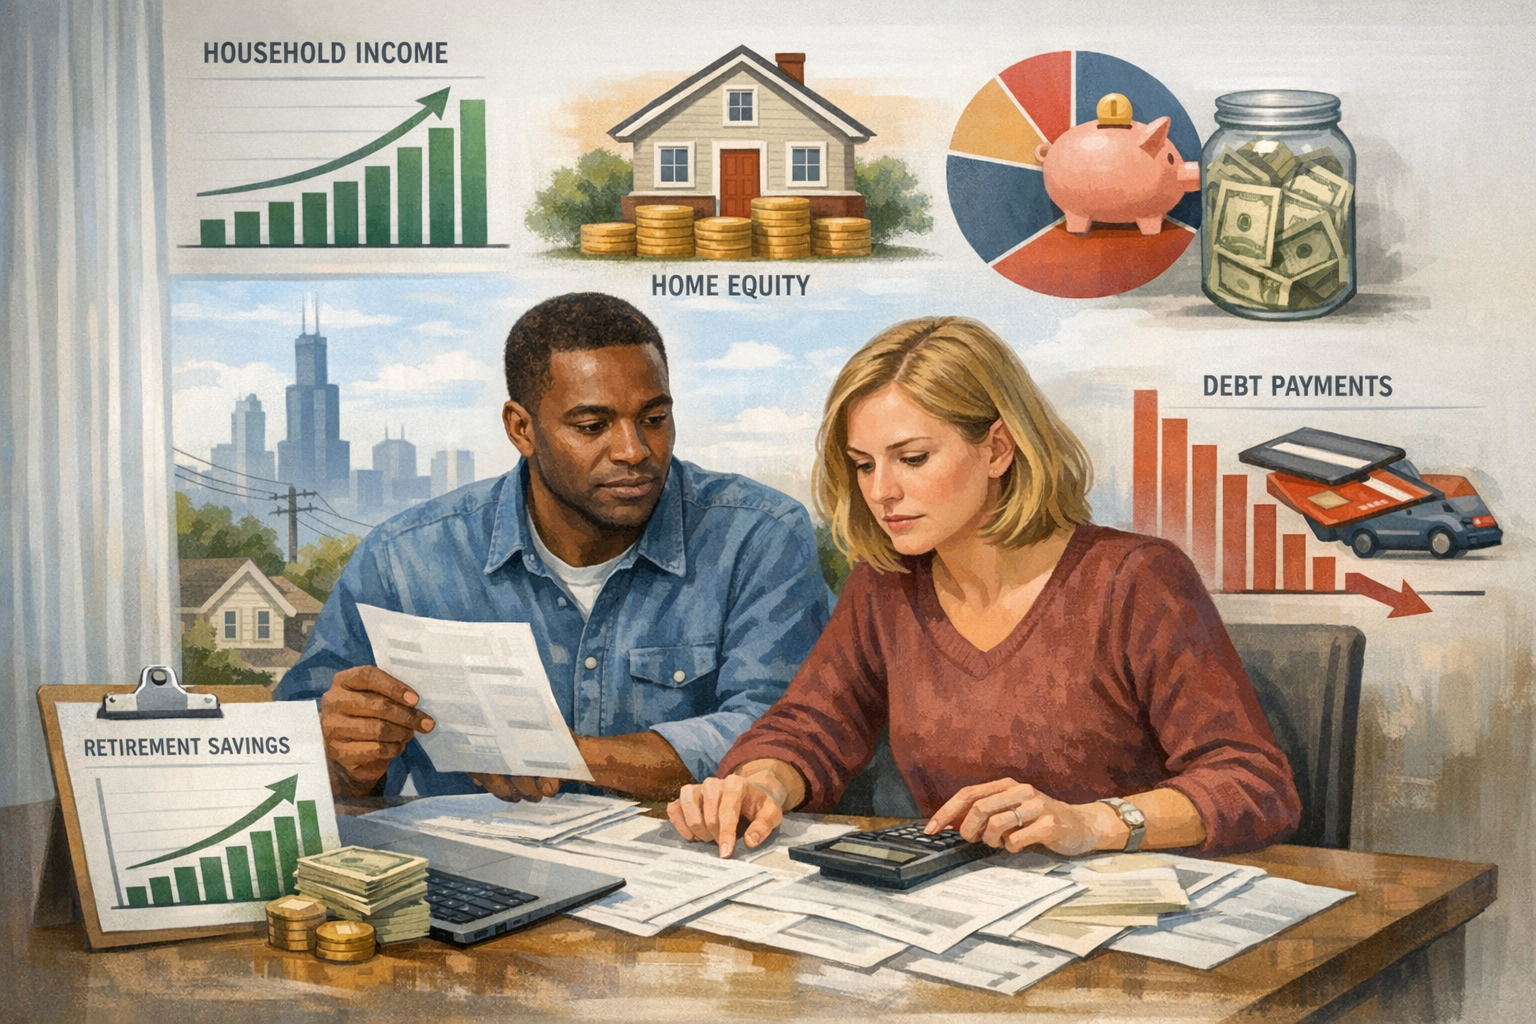
The Federal Reserve’s latest Survey of Consumer Finances offers a mixed picture of U.S. household finances: the typical family made real income gains from 2022 to 2025, household wealth edged higher at the median, and retirement account participation increased. At the same time, more families were carrying high debt payments relative to income.
The Fed released the 2025 survey results on Oct. 9, 2026. The survey is conducted every three years for the Federal Reserve by NORC at the University of Chicago and is designed to represent American families selected from 119 geographic areas, including metro areas and rural counties.
No Schaumburg-specific results were included in the Fed’s public release. For readers in Schaumburg and the Chicago suburbs, the findings are best understood as national benchmarks rather than a direct local measure. Local outcomes may differ because housing costs, wages, property taxes, commuting patterns and job markets vary across Illinois communities.
What the data shows
The Fed reported that real median family income rose 7% from 2022 to 2025, reaching $82,200. Real means the figures are adjusted for inflation, which makes the comparison more useful than looking only at dollars before price changes.
The average, or mean, family income moved in the opposite direction, falling 6% to $145,200. That gap between median and mean matters. The median represents the middle family, while the mean can be pulled up or down by very high or very low values. When the two measures move differently, it can signal that gains and losses were not distributed evenly across households.
Median net worth increased 2% to $215,900, while mean net worth rose 7% to $1.24 million. Net worth is the value of what a family owns, such as housing equity, savings and investment accounts, minus what it owes, such as mortgages, credit card balances, student loans or auto loans.
Housing remained a major part of household balance sheets. The homeownership rate was 66% in 2025, roughly unchanged from 2022. Among homeowners, the median net housing value rose to $230,000 from $218,900.
Retirement accounts, stocks and debt
The Fed said retirement-plan participation was about 65% and increased between 2022 and 2025. For families with retirement accounts, balances also rose. Retirement accounts can include employer-sponsored plans such as 401(k)-type accounts and individual retirement accounts. These accounts may provide tax advantages, but they can also involve investment risk, contribution rules, withdrawal limits and fees.
Stock-market participation slipped from 58% of families in 2022 to 56% in 2025. Among families that owned stocks, median holdings increased 36%, from $56,900 to $77,400. Stock ownership in the survey can include direct stock holdings and stock funds held through retirement or other investment accounts. Stocks can rise or fall sharply, so higher balances can reflect market performance, contributions, or both.
Debt remained widespread. The share of families with any debt was about 77%, and the Fed said median and mean debt outstanding were roughly unchanged. But the share of families with debt payment-to-income ratios above 40% rose from 6.5% to 8.6%, the highest level since the 2013 survey.
A debt payment-to-income ratio compares required debt payments with income. A higher ratio can leave less room for rent or mortgage payments, groceries, medical bills, insurance, savings and emergencies. It does not automatically mean a household is insolvent, but it is a warning sign that finances may be more vulnerable to job loss, higher interest rates or unexpected expenses.
Why it matters
The survey helps policymakers, researchers and the public understand how family finances changed after several years marked by inflation, higher interest rates and shifting asset prices. The results show that the typical family’s inflation-adjusted income improved, but they also point to uneven outcomes: average income fell, average wealth rose faster than median wealth, and a larger share of families faced heavy debt-payment burdens.
For households in Schaumburg and across Illinois, the report provides a useful checklist of financial pressure points to watch: housing equity, retirement savings, exposure to stock-market swings, consumer debt and the size of monthly payments relative to income. The survey does not say what any individual household should do, but it highlights the areas where small changes in rates, prices or income can have large effects.
Educational context for readers
This article is for general educational purposes only and is not personalized financial, investment, tax, credit, lending, housing, retirement or legal advice.
When reading reports like the SCF, it helps to ask several plain-language questions: Are figures adjusted for inflation? Is the number a median or an average? Does the result describe all families or only families that own a particular asset, such as a home, stock account or retirement plan? Are debts measured by total balance or by monthly payment burden?
Fees and terms also matter. Retirement plans and brokerage accounts may include administrative fees, fund expenses or trading costs. Loans and credit cards can carry interest charges, late fees and variable rates. Mortgages may include closing costs, taxes, insurance and rate-reset risks depending on the loan type. A balance-sheet snapshot may not show these ongoing costs clearly.
Common warning signs for financial strain include relying on new borrowing to make required payments, making only minimum credit card payments for long periods, missing due dates, using retirement money for routine expenses, or having little cash available for emergencies. Those signs do not have the same meaning for every household, but they can indicate that debt or fixed costs are crowding out flexibility.
Uncertainties and limits
The SCF is a major national survey, but it is not a real-time monthly indicator and it is not a Schaumburg household survey. The results cover changes from 2022 to 2025 and can be affected by sampling variation as well as real economic changes.
The Fed’s release highlights headline figures, while deeper interpretation requires reviewing the full report, chartbook and underlying data. Regional and local differences remain important. A Chicago-area household’s experience with home values, commuting costs, wages or taxes may not match the national median.
Sourcesfederalreserve.gov other20261009afederalreserve.gov scfindexnorc.org scffederalreserve.gov other20260513afederalreserve.gov 2026 economic well being of us households in 2025 executive…
More in Economy Fed’s September 2026 projections point to only gradual rate declinesSep 29, 2026 Why the Treasury’s “Checking Account” Matters for Rates and Market LiquiditySep 29, 2026
Share this articleFacebookXLinkedIn
Explore SchaumburgEvents →Things to Do →Coupons →Classifieds →Jobs →Videos →
SPONSORED

Business Name
Service • Service
Short description of the business.
Licensed

Paid placement. We don't endorse this business. Please verify licenses before hiring.
Keep reading
More local news and guides from Schaumburg Marketplace.